
Help clients understand and prepare for the challenges of long-term care
10/02/2026 — Healthcare and retirement have always been intertwined. We know that healthcare costs are one of the biggest variables in a retiree’s budget, but healthcare decisions today can impact retirement healthcare costs in ways many retirees may not have even considered.
For example, innovative treatments such as GLP-1s for weight loss and diabetes management may improve overall health and enable people to live longer and healthier lives, and at the same time add to client worries about outliving their retirement savings.
Our 2026 Nationwide Retirement Institute® Healthcare Costs Survey shows why conversations about healthcare belong at the center of retirement planning. This is especially true for those who are near or in retirement. Many older Americans worry about what they’ll pay out of pocket for healthcare, what Medicare will and will not cover, and whether these expenses will disrupt their retirement plans.
Some of the highlights from our survey of nearly 2,000 US adults include:
- Around three-quarters (74%) fear healthcare costs will go out of control in retirement.
- Around two-thirds (65%) are terrified of what healthcare costs may do to the plans they made for retirement.
- Nearly six in 10 (59%) current users expect a financial professional to advise them on the financial impact of GLP-1 medications or other health innovations.
For financial professionals, these insights reveal that clients increasingly see healthcare decisions and financial decisions as interconnected. For most Americans, healthcare costs are not a secondary retirement topic—they are integral to their overall retirement plan, just as important as saving rates, retirement income withdrawals and decisions on when to retire.
Here are three important insights that should serve as a foundation for your next healthcare planning discussion:
Rising healthcare costs and the potential health benefits of innovative treatments are reshaping how clients save and when they expect to retire
Households are already facing affordability challenges from higher consumer prices. When rising healthcare costs are added to these pressures, the effects can influence many present-day financial decisions, as evident in our survey.
That includes retirement planning. Our survey found that worries about healthcare costs are changing how much people are saving and when they are deciding to retire. For many households, an unexpected expense for a hospital stay or a visit to a medical specialist could translate into saving less, working longer and drawing down retirement assets—all of which can weaken retirement readiness.
- 55% say medical or health expenses have drastically reduced how much they saved or will be able to save for retirement.
- 59% worry healthcare costs will delay their plans to retire or stay retired.
Additionally, healthcare affordability issues can lead to financial tradeoffs that impact decisions on when and how to seek care. One timely affordability issue for some clients is GLP-1 medications. While just 10% of those surveyed are currently taking a GLP-1 drug, around 59% of users worry about how they will afford the medication after they retire.
Because of these tradeoffs, many GLP-1 users are rethinking important financial and retirement decisions. GLP-1 users tend to be more optimistic about their long-term health. However, over half (56%) say living longer may require more money for future healthcare expenses. Half of GLP-1 users (51%) also worry they may have to choose between paying for their medication and saving enough for retirement.
The important takeaway for financial professionals is to help clients plan for present and future healthcare decisions before any financial tradeoffs emerge. Starting these conversations can help clients not only prepare for future healthcare costs but also protect their long-term savings and help align their financial plans with evolving healthcare needs.
How to help clients: Talk about healthcare costs early and often in client conversations and integrate healthcare cost estimates into their retirement income plans. Help clients distinguish between costly annual out-of-pocket premium expenses and planning ahead for large or extended care needs.
Healthcare’s rapid evolution makes personalized retirement-cost planning essential as it presents both challenges and opportunities for long-term financial planning
While healthcare costs are a significant concern, a lot of people feel unprepared to plan for them. Many find it difficult to put a number on these future expenses. It’s hard enough to predict what could happen tomorrow, but the uncertainty of needing healthcare and the rapid pace of cost increases can cause people to postpone planning rather than take action.
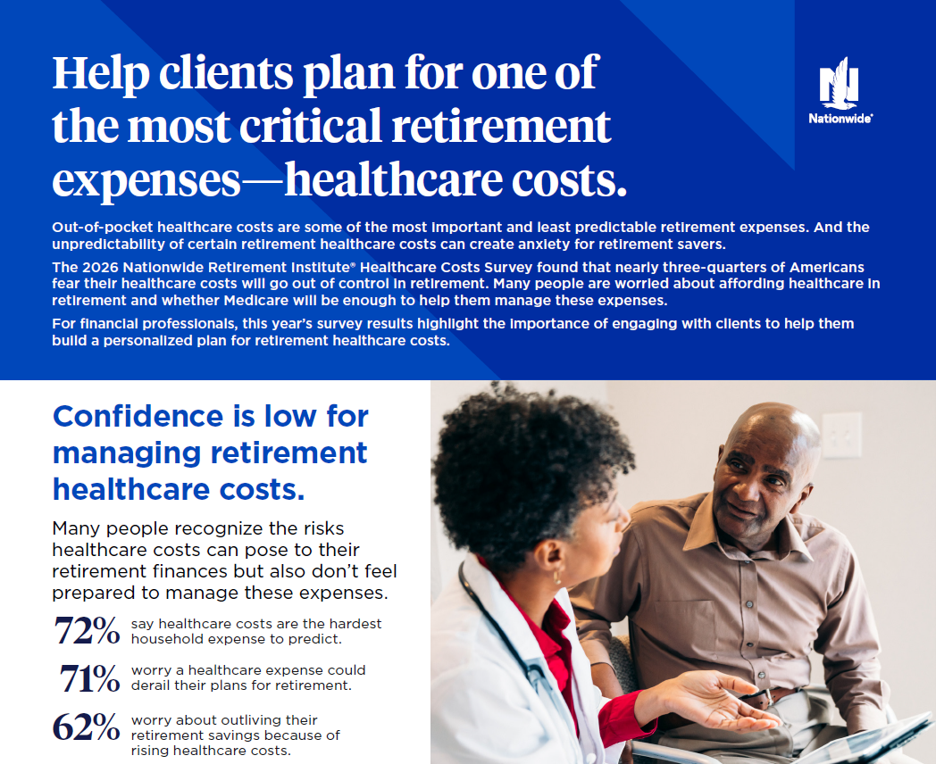
- 72% said healthcare costs are the hardest household expense to predict.
- Three in five (62%) worry about outliving their retirement savings.
Financial professionals should be aware of how clients view healthcare cost planning in context with their overall financial plan. Many clients are open to guidance on preparing for these future expenses; 85% of those surveyed said managing healthcare costs should be part of personal financial planning.
How to help clients: Become the go-to source for healthcare cost planning by presenting a personalized healthcare cost estimate. Be sure the estimate accounts for the impacts of inflation, longevity and the possibility of chronic conditions. Revisit this estimate as clients approach retirement or after significant life events.
Medicare knowledge gaps are leaving clients vulnerable to higher costs
Another reason for the lack of planning is tied to a lack of knowledge. This extends not only to healthcare costs in general but also to how decisions on Medicare coverage help manage these costs.
Clients may recognize the different Medicare options (i.e., deciding between original Medicare or a third-party Medicare Advantage plan) but they don’t understand how their choices could affect their premiums, access to their preferred healthcare providers, or out-of-pocket exposure. Around three in four survey respondents (74%) said they wished they had a better understanding of how Medicare coverage works. Moreover, 31% feel they don’t know what Medicare Advantage is—a common way for retirees to manage out-of-pocket healthcare costs.
Financial professionals have an opportunity to include healthcare costs in their planning discussions by focusing on Medicare knowledge and coverage gaps. Three-quarters of current clients (75%) would likely switch to a financial professional who could help them navigate their Medicare choices.
- What services are covered by Medicare Parts A-D (37%)
- Overall cost of Medicare coverage (36%)
- Out-of-pocket costs (33%)
How to help clients: Focus on Medicare education as a way to engage clients in healthcare cost planning and demonstrate the value of professional guidance. Help clients understand Medicare choices and premium implications in the context of the client’s full plan. Address eligibility and timing, coverage, total costs, out-of-pocket exposure and how changes in retirement income can raise or lower Medicare premiums.
Help your clients keep pace in a changing healthcare climate
Insights from this survey give financial professionals a timely opening to move clients from anxiety over affording healthcare costs to a more complete retirement strategy.
- Help clients estimate and stress-test future healthcare costs.
- Discuss with your clients how rising healthcare costs, including expenses for innovative treatments like GLP-1 medications, can significantly impact their retirement savings and income sustainability over time.
- Explain Medicare choices and premium implications in the context of the client’s full plan.
- Review healthcare assumptions during major life events, enrollment periods and annual plan updates.
- Using the client’s personalized healthcare cost assessment, identify potential sources of reliable or guaranteed lifetime income, where appropriate, to help address anticipated annual healthcare expenses.
Planning is a great way to address your clients’ concerns about future healthcare costs and give them a clearer understanding of how those costs fit within their retirement financial plan. A personalized estimate of retirement healthcare costs can be a starting point for your planning conversations and a way to bring structure to their retirement preparations.
As clients weigh today’s healthcare needs against tomorrow’s savings goals, your guidance can help them consider both sides of that equation and integrate them into their long-term financial plans. Healthcare costs may drive the planning conversation with clients, but the broader opportunity comes in helping them build a more resilient retirement plan.
Author
Holly Snyder
President of Nationwide Life Insurance
In her current role, which she assumed in 2019, Holly Snyder is responsible for all aspects of the life business, including business strategy and execution, managing life sales growth and profitability, product and business development, and fundamentally transforming the life new business processes to optimize the customer experience.
Trending articles
Social Security uncertainty creates a timely opening to educate clients on claiming age, retirement income planning, and broader financial needs. View insights from our survey.
Americans remain resilient, but 2026 challenges are reshaping financial success, with consumers leaning slightly more toward protection than growth. Learn more in our latest Index.
Learn how pets shape retirement happiness and health, and why financial professionals should understand clients’ pet priorities.