How to shape workable strategy for ownership transition
About Nationwide Retirement Institute Retirement savings & income
Health care costs & longevity
Legacy, estate & wealth transfer
Business growth, protection & transfer
Market & news
About Nationwide Retirement Institute
Succession planning stage 2: Planning
Key aspects of planning:
|
|
Succession planning is one of the most important — and most overlooked — aspects of business ownership. A clear, well-structured plan helps ensure that the business can continue, even if the owner steps away unexpectedly. It also protects the value of the company, supports employees, and provides clarity for family members and stakeholders.
In stage 1, we covered the discovery process: clarifying goals, identifying potential successors and setting a transition timeline. Stage 2 builds on that foundation, starting with a business valuation and eventually crafting a concrete, actionable plan. This stage is all about aligning succession objectives with actionable strategies and preparing for the events that will eventually trigger the transition.
For financial professionals, this is where the groundwork laid during discovery pays off. You can help business-owner clients weigh options, clarify expectations, and begin formalizing a succession structure that supports their goals and protects their legacy.
Start with a business valuation
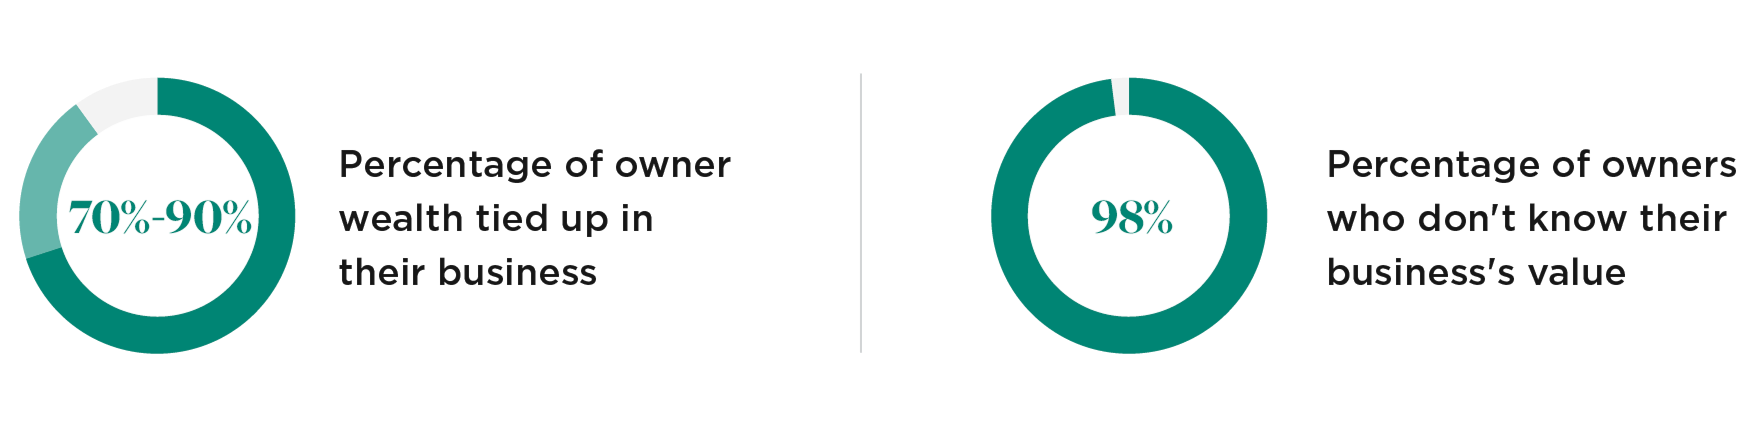
Valuation ties goals to reality and provides a financial baseline for any ownership transfer, whether that's a sale, a buyout or a gift. Yet nearly all business owners are in the dark about what their company is actually worth.1
Encourage clients to get a valuation early, even if it's informal. Knowing the value:
- Helps establish fair terms for a future sale or buyout
- Informs retirement and estate planning decisions
- Sets more realistic expectations for both owners and successors
- Helps owners determine funding and set up a funding mechanism
As circumstances change, the valuation can always be updated. But starting with a number — rather than a guess — creates needed clarity.
Explore succession options
Armed with the goals and valuation, the next step is to identify workable strategies. This includes determining:
Who will take over the business
How ownership will be transferred
What events will trigger that transfer
How the business transition aligns with family goals
Some plans may involve gifting the business to children. Others may call for a sale to a co-owner, a buyout by key employees or a third-party acquisition. In many cases, especially when multiple owners are involved, co-owners are the most natural successors. Planning early for buy/sell arrangements between partners can ensure stability and protect both the business and the departing owner’s family members. There’s no one-size-fits-all answer. What matters is that the path matches the owner’s priorities and the successor’s capabilities.
It’s also critical to explore what happens if a triggering event — such as death, disability or retirement — occurs unexpectedly. Having clear protocols in place now reduces the risk of conflict, chaos or loss of business value down the road.
PRO: Keeps business in the family
CON: Family dynamics can cause conflict
PRO: Already understands the business; continuity is built in
CON: May create imbalance or disputes among partners
PRO: Knows operations; is invested in success
CON: May lack capital or leadership readiness
PRO: May offer strongest financial payout
CON: Culture and job security risks for employees
Define your buy/sell agreement structure
For many businesses, a buy/sell agreement becomes the linchpin of the succession plan. This legal document lays out the terms for how and when ownership will transfer. Most commonly, these agreements are structured between existing owners and funded with life insurance, making co-owner succession one of the most practical and widely used approaches. While the buy/sell agreement itself will be drafted and executed in stage 3, the owner should consider what they would like it to include.
At a minimum, it should address:
Triggering events
These could be death, disability, retirement or a partner’s decision to exit the business
Valuation method
This could be based on a fixed price, a formula or third-party appraisal
Payment terms
Determine whether the purchase will be funded by a lump sum, installment payments or other means
Even family businesses need formal agreements. Without them, misunderstandings can turn into costly disputes. The goal isn’t to create distance. It’s to bring structure and predictability to what can be a highly emotional process. In fact, in some cases, formal agreements are critical in a family business to provide for family members who are either active or inactive in the business. Buy/sell agreements can also clarify what happens to ownership interests in difficult scenarios, such as divorce, bankruptcy or disputes among shareholders.
Match the plan to the successor
A strong plan is effective only if it works for everyone involved. For financial professionals, that means helping clients think through whether their chosen successor has the ability and resources to step into ownership.
In many cases where family is going to take over, the owner may not be looking for a full purchase price, so funding the actual sale may be less important than funding the equalization of inheritance among active and inactive family members. In many cases, the successor can’t afford a lump-sum purchase, and installment payments or phased ownership may make sense. Regardless of whether there is a lump sum to cover the cost or a substantial down payment, the terms need to reflect how and when those funds will become available.
Owners should also ensure that their estate plan and succession plan complement each other. That might mean equalizing inheritances among children who are active in the business and those who aren’t. Or it might mean preserving cash flow for the exiting owner during retirement. These considerations often lead to deeper planning discussions around tax strategy, estate planning and liquidity needs.
Prepare operations for ownership transition
In addition to legal and financial considerations, stage 2 should also involve operational aspects of the business. As part of the planning process, encourage clients to:
Document key business processes
Clarify roles and responsibilities
Strengthen the leadership bench
Reduce reliance on the current owner(s)
These steps serve 2 purposes: They make the business more attractive to a buyer or successor, and they make the actual transition smoother when the time comes.
Help owners move from vision to structure
Discovery is about vision. Stage 2 is about structure. This is the point in the process where you can help clients turn what they want into a plan that actually works. That means addressing valuation, legal mechanics, successor preparedness and operational readiness — well before the transition is triggered.
Too often, these conversations happen too late. By initiating them now, you help clients preserve what they’ve built, avoid painful missteps, and create a plan that supports long-term business continuity.
Up next is Stage 3: Implementation
That’s when decisions are formalized, documents are signed and funding strategies are put in place.
Want to print this article?
[1] Sources: M&T Bank (as cited in JEC-LLC, 2023); interVal (2023); Exit Planning Institute, State of Owner Readiness survey; Benchmark International (2022).