An example
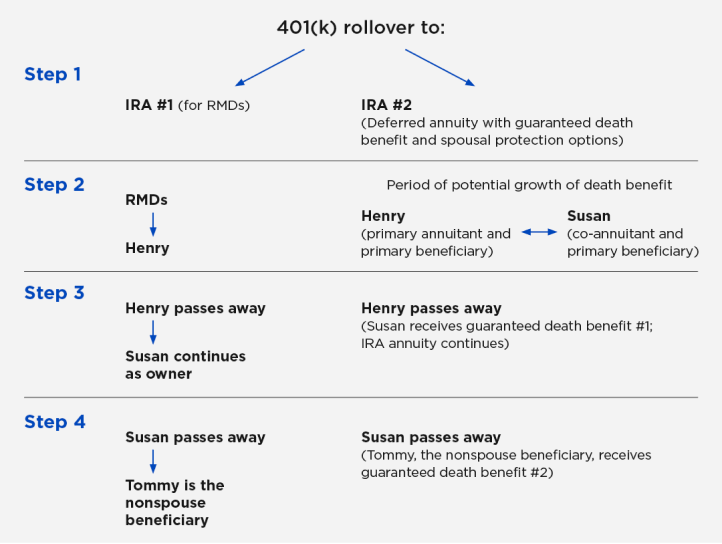
Upon his retirement, Henry rolled over $500,000 from his qualified plan into a traditional IRA and named his wife, Susan, the primary beneficiary. Henry wants to know that if he passes before Susan, she will receive the maximum amount of his IRA assets. After consulting with his financial advisor, Henry splits his IRA into two IRAs: one to cover RMDs and the other a Nationwide annuity with guaranteed death benefit and spousal protection features. Henry is owner and annuitant and Susan is named co-annuitant. Both Henry and Susan are named primary beneficiaries.
At age 73, Henry must begin taking required minimum distributions every year. The RMD amount for both of his IRAs will come from IRA #1, which was set up specifically for RMD withdrawals for as long as possible. As Henry is taking these RMDs year after year, the IRA #2 annuity guaranteed death benefit amount will remain untouched and may continue to grow.
If Henry passes away before Susan, she is allowed to continue both IRAs as her own and must take RMDs beginning at age 73. Susan will receive her RMDs from the remaining account balance of IRA #1. From IRA #2, Susan will receive the guaranteed death benefit. If she doesn’t take any distributions from IRA #2, the guaranteed death benefit will continue to grow for her beneficiary, their son, Tommy. Upon her death, Tommy will receive the remaining account value from IRA #1 and another guaranteed death benefit from the annuity in IRA #2.