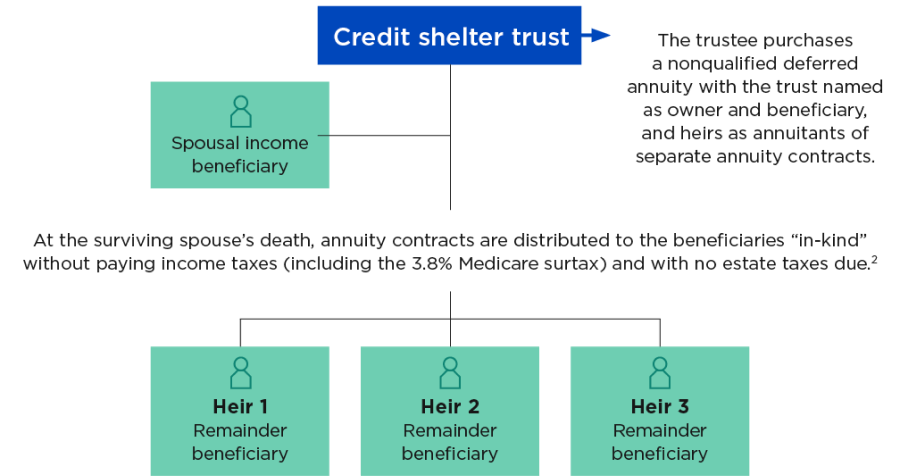
The trustee uses the trust assets to purchase three NQ deferred annuity contracts. Roger is named annuitant on one annuity contract, Renee on the second, and Rosa on the third. The trust is named as owner and beneficiary of all three contracts. Because all the trust beneficiaries are natural persons, the annuities should fall under the exception to the non-natural owner rule, and annuity gain is tax deferred.1
Upon the trust’s termination, or if the trust provisions allow distributions in-kind to the children, the NQ deferred annuities can be transferred from the credit shelter trust to the children without triggering gift or income taxes.2 Thereafter, the annuities will remain income tax deferred until the death of the respective owner/annuitant, or until voluntary distributions are made from the contracts.
We know that by using NQ deferred annuities in the trust, the trustee will be able to take advantage of several of the benefits and features provided by these contracts. In addition, using NQ deferred annuities as funding vehicles in a trust also provides:
- Tax deferral on annuity growth1: Any growth produced by the NQ deferred annuity contracts will remain tax deferred until distributions are made from the contract,3 whereas if the assets are invested in mutual funds (or some other taxable instrument), income taxes and the Medicare surtax may come into play.
- Distributions during the surviving spouse’s life3: The surviving spouse has a right to receive the income and often has a right to receive the principal (under certain limited criteria) from the trust. The trust may name all of the children as beneficiaries of the trust to receive distributions for any reason. As long as distributions of taxable income from the NQ deferred annuity are distributed to a trust beneficiary in the same calendar year, the trust will not pay income tax on the distribution. The beneficiary will pay income taxes on the taxable income at the beneficiary’s tax rate.3
Please consult with a tax advisor regarding application of the additional 10% premature distribution tax (10% tax) on taxable distributions from a deferred annuity owned by a trust. In PLR 202031008, the IRS ruled the 10% tax applies to taxable distributions from a deferred annuity owned by a non-grantor trust, with no allowable exceptions.