Wade D. Pfau, Ph.D., CFA®, RICP®, Professor of Practice, The American College of Financial Services
Michael Finke, Ph.D., CFP®, Professor of Wealth Management, The American College of Financial Services
Wade D. Pfau, Ph.D., CFA®, RICP®, Professor of Practice, The American College of Financial Services
Michael Finke, Ph.D., CFP®, Professor of Wealth Management, The American College of Financial Services
Crafting retirement income strategies for clients is a highly personalized process with the ultimate goal of helping to ensure that clients’ assets last throughout their lives (or longer). Among the many considerations are 2 main client risks: life expectancy and investment risk.
As life expectancies increase, the probability of depleting savings over an extended retirement horizon grows. Simultaneously, market downturns can erode portfolio values, compounding the challenge of maintaining a sustainable withdrawal rate. This can be particularly true for clients with higher levels of risk tolerance, as their portfolios may be inherently more susceptible to market volatility.

Retirement income plans often use systematic withdrawals from investment portfolios. But this approach carries inherent risks.
Consider a retiree requiring $40,000 annually from a $1 million portfolio. A traditional 4% withdrawal strategy assumes historical market returns will support this level of spending. However, if the first few years of retirement coincide with market losses, withdrawal rates may become unsustainable. Without a guaranteed income component, retirees are forced to either reduce spending or risk portfolio depletion.
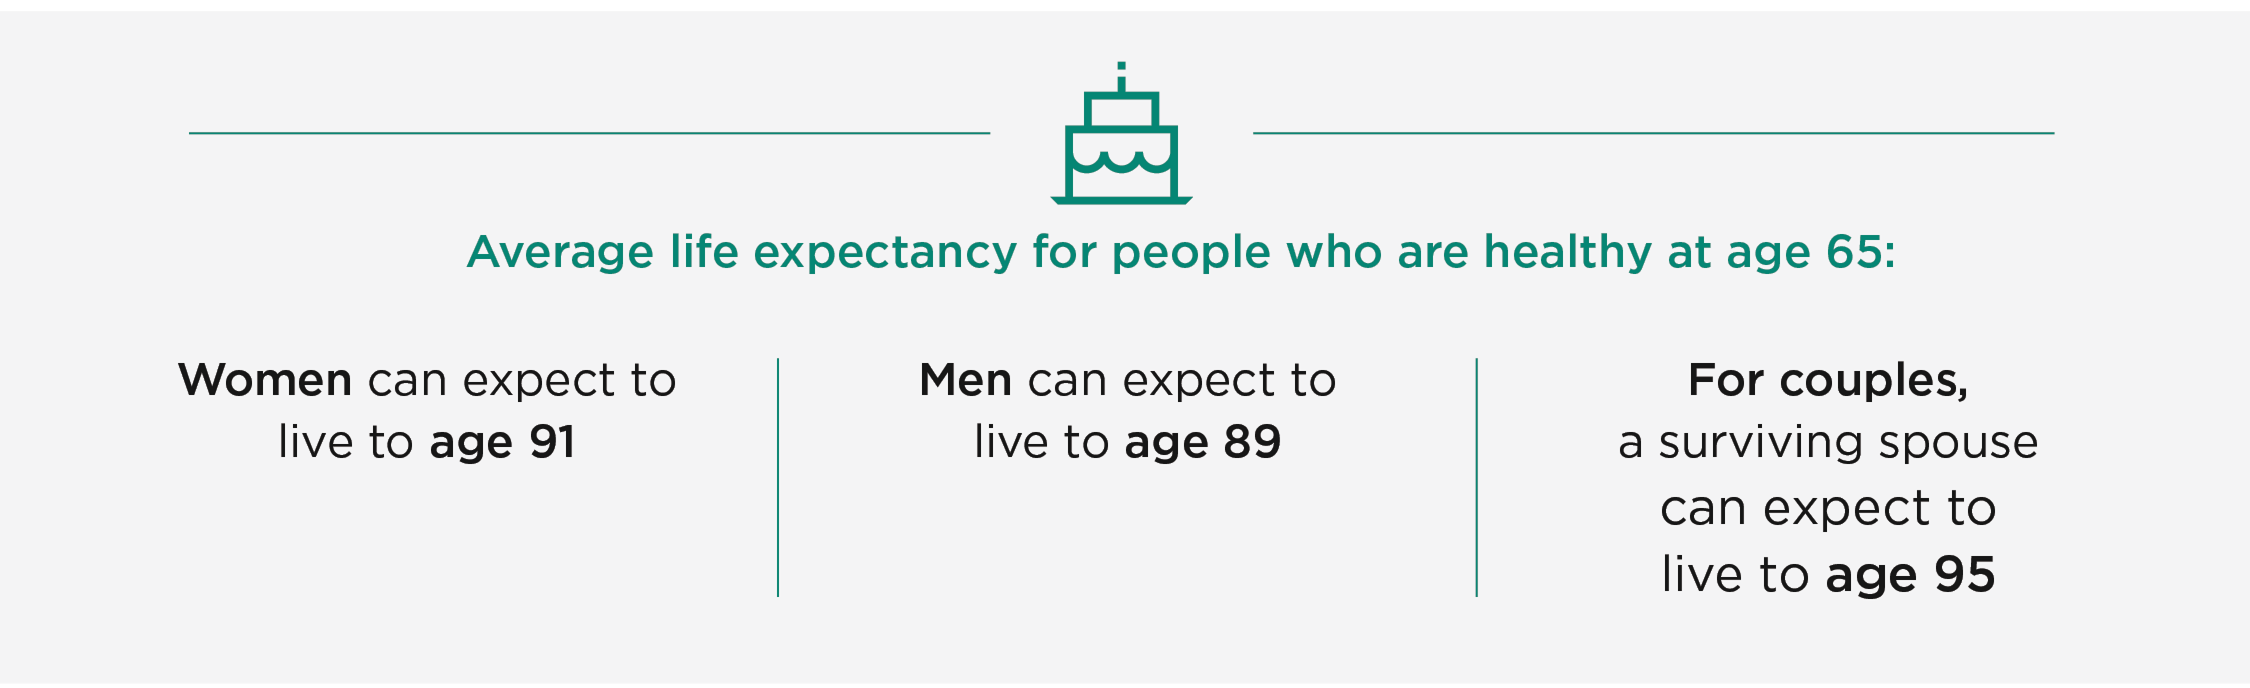
Increased longevity exacerbates this challenge. Among people who are healthy at age 65, men can expect to live to age 89; women to age 91. For a healthy, 65-year-old couple, there’s a high likelihood that at least one partner will live into their 90s.1 Planning for a static 25- or 30-year retirement period underestimates the financial burden of this extended longevity.
Products like annuities and in-plan lifetime income options transfer longevity and market risks to an insurer, providing a guaranteed income stream that supports retirement spending with greater certainty. Unlike systematic withdrawals, which rely on market performance, these investments help ensure a more predictable payout — regardless of investment returns or lifespan.
For example, Figure 1 shows that a retiree seeking $20,000 in annual income could allocate $347,588 to Treasury bonds, which would cover 25 years of withdrawals. However, this approach still carries a 20% probability of outliving savings. By contrast, a fixed immediate annuity with a 7.39% payout rate could deliver the same income for life with a lower capital requirement of $270,636, freeing up over $75,000 for lifestyle expenses or legacy planning

Here are the key advantages of adding protected income options to retirement portfolios:
Identify clients who are in or nearing retirement
Narrow the list to those who may have a longer life expectancy or a higher tolerance for risk
Consider protected income options to help safeguard essential spending needs
[1] Society of Actuaries 2012 individual annuity mortality tables adjusted for 1% annual improvement.