How a diversified approach can help clients
About Nationwide Retirement Institute Retirement savings & income
Health care costs & longevity
Legacy, estate & wealth transfer
Business growth, protection & transfer
Market & news
About Nationwide Retirement Institute
Minimizing taxes on Social Security benefits
Key highlights
- Social Security benefits offer tax-advantaged income to retirees throughout retirement.
- Diversifying where clients save can help lessen taxes on Social Security benefits and other income in retirement.
- Demonstrate your value by creating a tax-efficient withdrawal strategy to help clients minimize taxation of Social Security benefits.
2 out of 3 affluent individuals say tax knowledge tops the list of important considerations when selecting a financial adviser.
Your clients may dislike taxes even more now than they did just a few years ago. According to a recent Gallup study, attitudes about federal income taxes in the U.S. are the worst in about 20 years. 6 in 10 Americans think their taxes are too high, according to the study. That’s up 3% from 2024 and 13% higher than in 2020.1
As a financial professional, this gives you an opportunity to provide a service that’s not only critical to your clients’ financial success but also highly valued by them: helping to minimize their tax burden. In fact, 2 out of every 3 affluent individuals say tax knowledge tops the list of important considerations when selecting a financial professional.2
There are a lot of ways to help clients plan for taxes in retirement. Many investors don’t understand that income taxes could be their single largest expense after they retire. You can provide valuable guidance by educating them on this fact and helping them implement strategies to minimize the expense. A great place to start is with the foundation of their retirement income: Social Security benefits.
Case studies: Diversified income sources can reduce tax burdens
Where retirement income is drawn from makes a big difference in how much of a client's Social Security benefits are taxed (or even if they’re taxed at all). Let’s explore case studies of 2 retired couples.
Couple 1
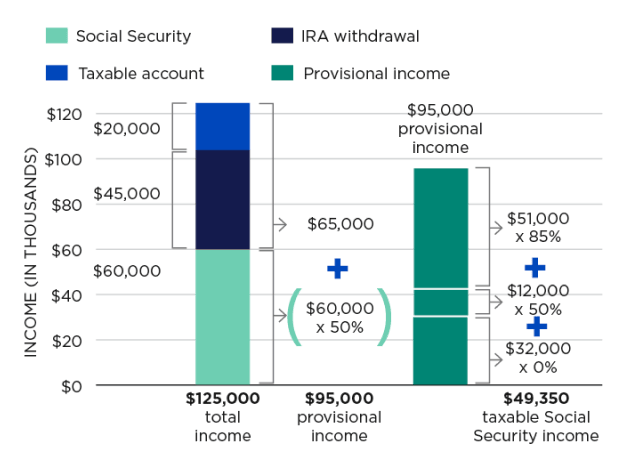
Both in their early 70s, married and filing taxes jointly, they want income of just over $10,000 per month ($125,000 per year). Their combined Social Security benefits fulfill about half of that, so they draw from 2 other sources:
$60,000 combined Social Security benefits
+$45,000 traditional IRA (ordinary income)
+$20,000 taxable account (long-term capital gains)
=$125,000 annual pre-tax income
Result
Couple 1’s annual provisional income is $95,000, making nearly $50,000 of their $60,000 in total annual benefits taxable.
Couple 2
These folks are also both in their early 70s, married and filing taxes jointly. They too want income of just over $10,000 per month ($125,000 per year). Their combined Social Security benefits fulfill about half of that, and so they draw from 2 other sources:
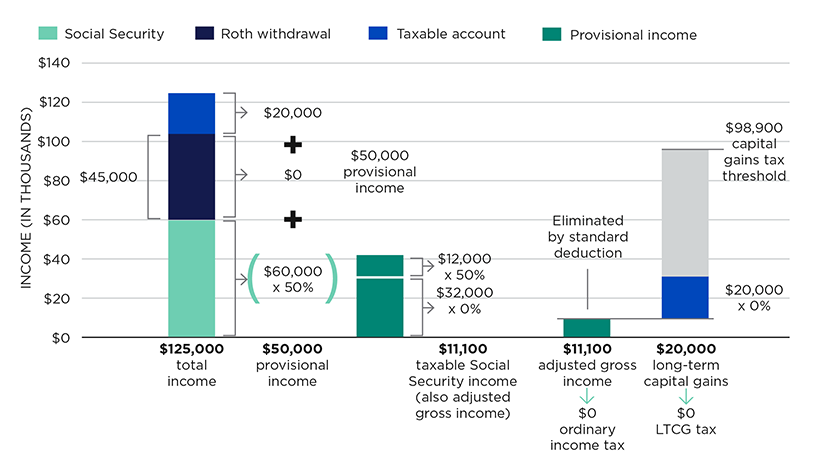
$60,000 combined Social Security benefits
+$45,000 Roth IRA (not taxable)
+$20,000 taxable account (long-term capital gains)
=$125,000 annual income (no income taxes owed)
+$45,000 Roth IRA (not taxable)
+$20,000 taxable account (long-term capital gains)
=$125,000 annual income (no income taxes owed)
Result
Couple 2’s annual provisional income is $45,000 lower and totaled just $50,000 (50% of their Social Security benefits, or $30,000, plus $20,000 in income from their taxable account). That means their Social Security benefits are roughly 80% tax-free. As a bonus, Couple 2 also owes $0 in long-term capital gains taxes because taxable income remained low enough to keep them in the 0% bracket.
| Couple 1 | Couple 2 | |
|---|---|---|
| Provisional income | ||
| 50% of Social Security benefits | $30,000 | $30,000 |
| Tax-deferred accounts: Traditional IRA | $45,000 | • |
| Taxable account: long-term capital gains | $20,000 | $20,000 |
| Tax-free accounts: Roth IRA and HSA | • | $45,000
(not included in provisional income) |
| Total Provisional Income | $95,000 | $50,000 |
| Portion of Social Security benefits subject to taxation | 82.25% | 18.5% |
Tax management strategies
A Roth IRA conversion allows your clients to move money from a traditional IRA into a Roth IRA. While the conversion itself is a taxable event, future withdrawals from the Roth IRA in retirement are tax-free and don’t contribute to Social Security provisional income.
By carefully balancing withdrawals from taxable accounts, such as brokerage accounts, and tax-deferred accounts, such as traditional IRAs and 401(k) accounts, you can manage your client’s adjusted gross income to keep it below the threshold at which Social Security benefits would be taxed.
HSAs can provide a triple tax benefit. Contributions are tax deductible, growth is tax free, and withdrawals for qualified medical expenses are tax free. After age 65, HSA funds can be withdrawn for any reason without penalty, although income tax applies to nonmedical withdrawals. Importantly, tax free withdrawals don’t count toward provisional income.
Encourage clients to invest in tax-efficient strategies such as cash value life insurance or using index funds, ETFs or tax-managed funds in taxable brokerage accounts. These can help provide income that is either not taxed or taxed at reduced rates, keeping the client’s overall income lower and potentially reducing taxes on Social Security benefits.
For clients who have other income sources, delaying Social Security benefits can sometimes result in larger levels of lifetime benefits and lower overall taxable income earlier in retirement. However, the decision to delay benefits should be balanced against the client’s overall financial picture and life expectancy.
For clients who are charitably inclined, qualified charitable distributions (QCDs) from an IRA can satisfy required minimum distributions (RMDs) while excluding the distribution from income, potentially reducing the tax on Social Security benefits.
Learn how Social Security benefits are taxed and three tips to be sure your clients are taking by downloading our full white paper.
[1] "U.S. Perceptions of 'Fair' Income Taxes Hold Near Record Low," Gallup, April 2025.
[2] "Build your tax and financial planning advisory services," Association of International Certified Professional Accountants (AICPA & CIMA), (accessed December 2025).
FOR FINANCIAL PROFESSIONAL USE — NOT FOR DISTRIBUTION TO THE PUBLIC
This material is not a recommendation to buy or sell a financial product or to adopt an investment strategy. Investors should discuss their specific situation with their financial professional.
This information is general in nature and is not intended to be tax, legal, accounting or other professional advice. The information provided is based on current laws, which are subject to change at any time, and it has not been endorsed by any government agency. Nationwide and its representatives do not give legal or tax advice. An attorney or tax advisor should be consulted for answers to specific questions.
Several assumptions are used in this white paper; changing any assumption or multiple assumptions may produce dramatically different results. All examples are purely hypothetical in nature and are not representative of any specific client situation. The examples do not constitute tax, legal or financial advice. Please seek appropriate legal or tax counsel before implementing any of the strategies discussed herein.
Federal income tax laws are complex and subject to change. The information in this white paper is based on current interpretations of the law and is not guaranteed. It should be regarded as educational information on Social Security and is not intended to provide specific advice. If you have questions regarding your particular situation, you should contact the Social Security Administration and/or your legal or tax advisors.
Before investing, clients should consider vehicle and investment objectives, risks, charges and expenses. Investing involves market risk, including possible loss of principal, and there is no guarantee that investment objectives will be achieved.
Nationwide Investment Services Corporation (NISC), member FINRA, Columbus, Ohio. The Nationwide Retirement Institute is a division of NISC.
Nationwide, the Nationwide N and Eagle, Nationwide is on your side and Nationwide Retirement Institute are service marks of Nationwide Mutual Insurance Company.
© 2026 Nationwide