Insights from the Nationwide Retirement Institute’s long-term care survey
About Nationwide Retirement Institute Retirement savings & income
Health care costs & longevity
Legacy, estate & wealth transfer
Business growth, protection & transfer
Market & news
About Nationwide Retirement Institute
Key highlights
- Many Americans hold misconceptions about long-term care (LTC) that can delay or derail effective planning
- Clients are open to LTC discussions but often wait for financial professionals to initiate them
- LTC insurance is often misunderstood — especially regarding cost, timing and coverage
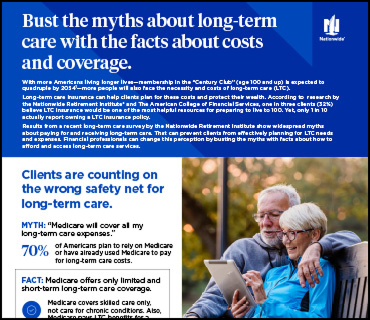
Retirement brings both opportunities and challenges, and many Americans may live longer than expected. The U.S. Census Bureau projects that the number of people reaching age 100 will quadruple by 2054.1 Yet many are potentially entering later life without proper protection.
A recent Nationwide Retirement Institute® survey reveals widespread LTC misconceptions. As clients face the realities of longer retirements, you can help by addressing these myths and explaining how LTC coverage supports future planning.
Common LTC myths
1. Medicare will cover all LTC expenses.
70% of those surveyed plan to rely on Medicare or have already used Medicare to pay for LTC costs. However, Medicare only covers some short-term skilled care — not chronic conditions — for up to 100 days, with significant co-pays starting after 20 days.
Solution: Help clients build a personal safety net for LTC costs.
2. LTC insurance is too expensive.
38% of people cite cost as the top reason for not prioritizing having LTC insurance, yet 64% overestimate the monthly premium of an LTC plan presented to them. After seeing accurate estimates, 47% were more likely to consider purchasing similar coverage.
Solution: Present a range of LTC coverage options to encourage consideration.
3. Clients think they already have LTC coverage.
22% of respondents believe they’re covered, but only 3% to 4% own a policy. Many confuse LTC coverage with health or disability insurance.2
Solution: Clarify what LTC insurance covers and the gaps it fills.
4. LTC coverage should be purchased later in life.
42% of Americans think the right time to purchase is around age 60 or later, but earlier is often better. Coverage is more affordable and accessible between ages 50 and 55.
Solution: Start LTC planning conversations earlier.
LTC conversations begin with you
One of the biggest reasons that clients give for not discussing LTC costs with their financial professionals is a simple one: Their financial professional hasn’t brought it up as a planning topic (34% said so).
Clients are open to having conversations about long-term care planning with their financial professionals. In our survey, 66% said they trust a financial professional to tell them when to buy LTC insurance.
You can start LTC conversations with clients by using empathy and understanding to break down misconceptions about cost and coverage, discussing the impacts that informal care can have on family members, and presenting solutions that are most suitable for them.
A proactive approach to LTC planning is more important than ever. As a financial professional, you play a key role in your clients’ lives by helping them prepare for potential long-term care needs, whether it’s for themselves, their parents or other family members.
For more LTC insights from our survey, check out our infographic.
[1] “U.S. centenarian population is projected to quadruple over the next 30 years,” Pew Research Center, (Jan. 9, 2024).
[2] “Five Reasons to Discuss Long-Term Care Insurance Options With Your Clients” LIMRA, November 7, 2024
The research was conducted online in the United States from March 17 to April 7, 2025, by The Harris Poll on behalf of Nationwide. The study surveyed 1,324 Americans ages 29 and up with household income of $75,000 or more.